
The three-bucket standard
| Bucket | Definition | Example from this site |
|---|---|---|
| Fact | Verifiable against a primary source, cited | “A 50% drawdown requires a 100% gain to recover.” Arithmetic. |
| Convention | How the industry does it. Defensible, not proven optimal. | “Risk no more than 1% per trade.” Widely used, not a law of nature. |
| Opinion | Our judgement, argued, labelled as ours | “The evidence that order blocks outperform ordinary demand zones is anecdotal and selection-biased.” |
Sourcing
We cite primary sources, not each other. The RSI and ATR are cited to Wilder's New Concepts in Technical Trading Systems (1978), not the fifteenth paraphrase. Loss aversion to Kahneman and Tversky (1979). Turnover to the BIS Triennial Survey. Real yields to the U.S. Treasury.
Where we are uncertain, we say so. Where a relationship is a tendency and not a rule, we write “frequently,” not “always,” and we tell you to test it yourself.
Trade examples
Of the fourteen trade examples across our guides, six are losses. That ratio is deliberate.
Charts of real price data are a different thing from trade examples: see real market data below.
Real market data, and how we publish maps
Trade examples are composites. Market data is not. The charts and statistics on our gold zone map pages are drawn by code from real price data, and none of them is a trade example or a record of a position.
- What a map is. A set of price bands with a stated distance, a measured probability and an invalidation line. It is structural analysis: not a signal, not a recommendation and not a trade.
- Only after it has expired. We show maps after the fact. They are examples of a method, never live levels and never trade signals.
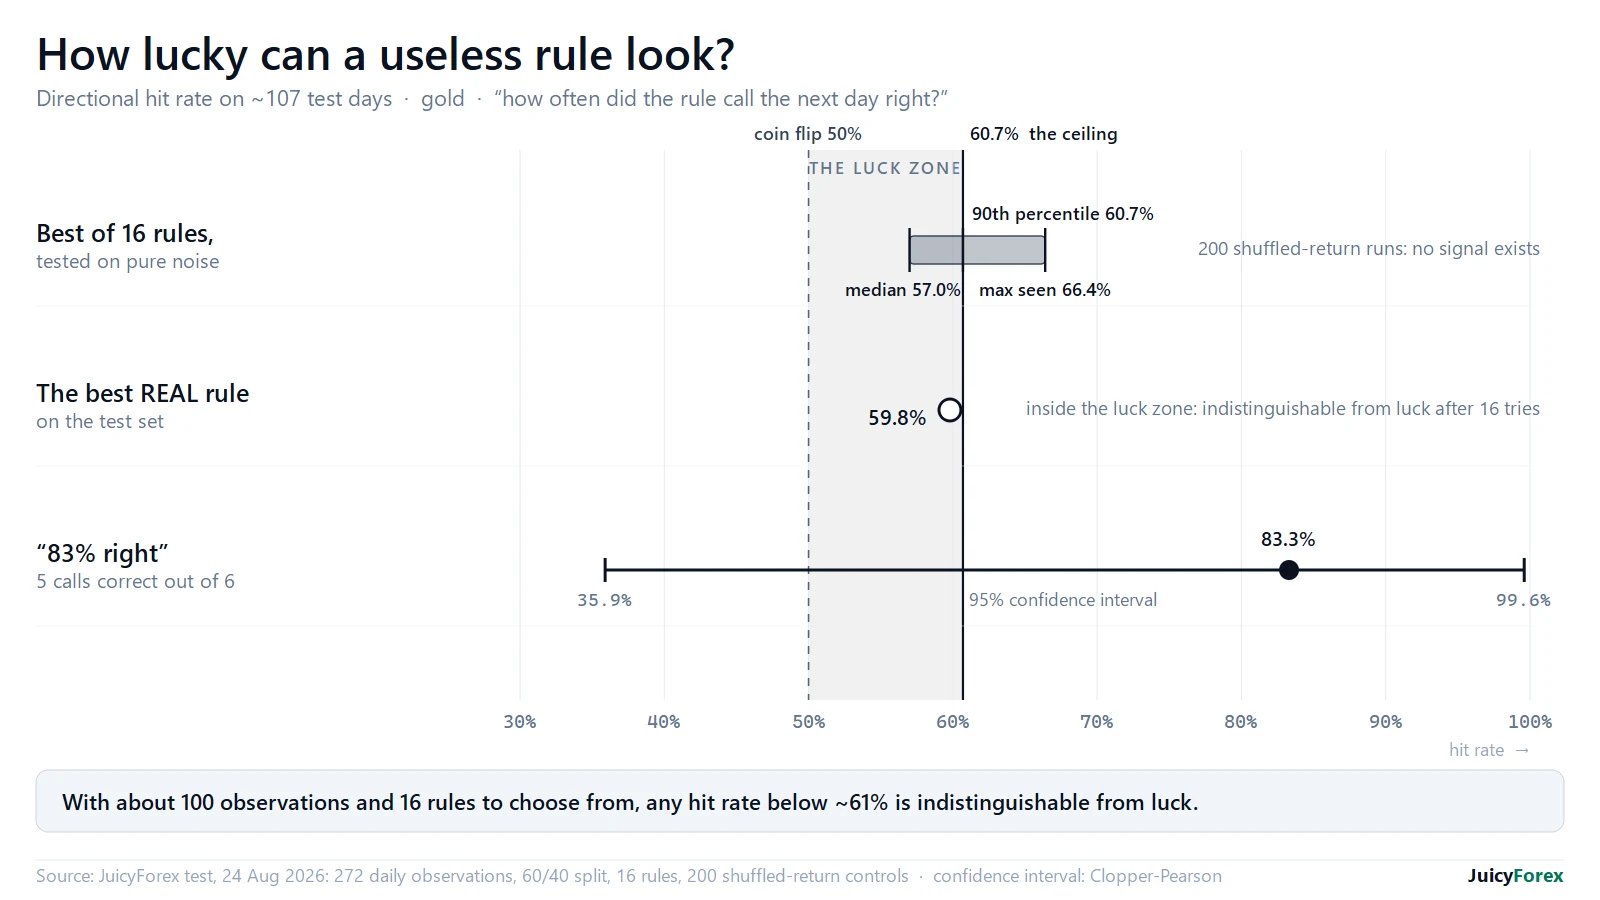
- Failures included. Archives show every map we can score from the period (leaving out test runs, exact duplicates and maps with no later prices saved), the misses and the voided zones with them, say where maps are missing, and say plainly when a sample is too small to show skill.
- Drawn from data, never mocked up. Every chart is drawn by code from price data or from the dated results of our own tests, and is not edited by hand. None comes from an image generator, and none is a stock image or a screenshot chosen for its result. Sources and dates are stated under each figure.
- Measured, then cited. Every number comes from the stated data or from a dated study note, and the figure says which. Where an earlier study on a different dataset gave a different magnitude, we say so, and say which part held.
Corrections log
Corrections are published, dated, and describe what was wrong. We do not silently edit.
| Date | Pages | What was wrong | What it says now |
|---|---|---|---|
| 10 Jul 2026 | Homepage, Beginner Guide, Strategy & Risk | We wrote that a 45% win-rate system produces ten consecutive losses “close to certainly” across 300 trades. Building the losing-streak calculator and validating it against a 40,000-run Monte Carlo showed the true probability is about 29%. | Ten in a row is a career event: roughly one-in-three within any 300 trades, ~68% across 1,000. Seven in a row, at 88%, is the base case. |
| 10 Jul 2026 | Homepage, Strategy & Risk | We described the probability of seven consecutive losses at a 40% win rate over 200 trades as “comfortably above 50%.” Understated. | It is approximately 91%. Not a tail risk. The base case. |
You can reproduce both figures with our losing streak calculator. If it disagrees with anything we have written, the calculator is right and we want to know.