
Facing the worst US inflation in about four decades, with headline CPI peaking near 9% in mid-2022, Powell's Fed ran the fastest hiking cycle in a generation. It took rates from near zero in early 2022 to a restrictive range by mid-2023, while draining its balance sheet. It is the chapter that most defines his tenure.
The problem
By 2022 US inflation had climbed to levels not seen in about forty years. Headline CPI peaked near 9% in the middle of the year. The causes were tangled: pandemic supply shocks, enormous fiscal and monetary stimulus and an energy spike. The result was clear. Inflation was far above the Fed's 2% target and proving persistent, not transitory as the Fed had earlier hoped.
Having been slow to react in 2021, the Powell Fed faced a credibility test. It had to bring inflation down decisively, or risk it becoming entrenched.
The response
The Fed's answer was force. From a near-zero policy rate in early 2022, it raised rates at the fastest pace in a generation. Several outsized hikes were far larger than the usual quarter-point step. The policy rate reached a restrictive range by mid-2023.
Alongside the hikes, the Fed began quantitative tightening, shrinking the balance sheet it had ballooned during the pandemic and draining liquidity. See QE and QT. It was one of the most aggressive tightening campaigns in the Fed's modern history.
The Jackson Hole message
At the Jackson Hole symposium in 2022, Powell gave an unusually short, blunt speech. He stressed that restoring price stability would keep policy restrictive "for some time" and would bring "some pain" to households and businesses.
The message was deliberate. After being caught out by inflation, Powell wanted no doubt about the Fed's resolve. Markets took it as hawkish and repriced. It shows how a Chair's tone alone can move the whole board.
What it did to markets
The tightening rippled through everything. Rapidly rising real yields and a surging dollar pressured risk assets. Bonds suffered one of their worst years on record as yields jumped. Rate-sensitive sectors repriced hard.
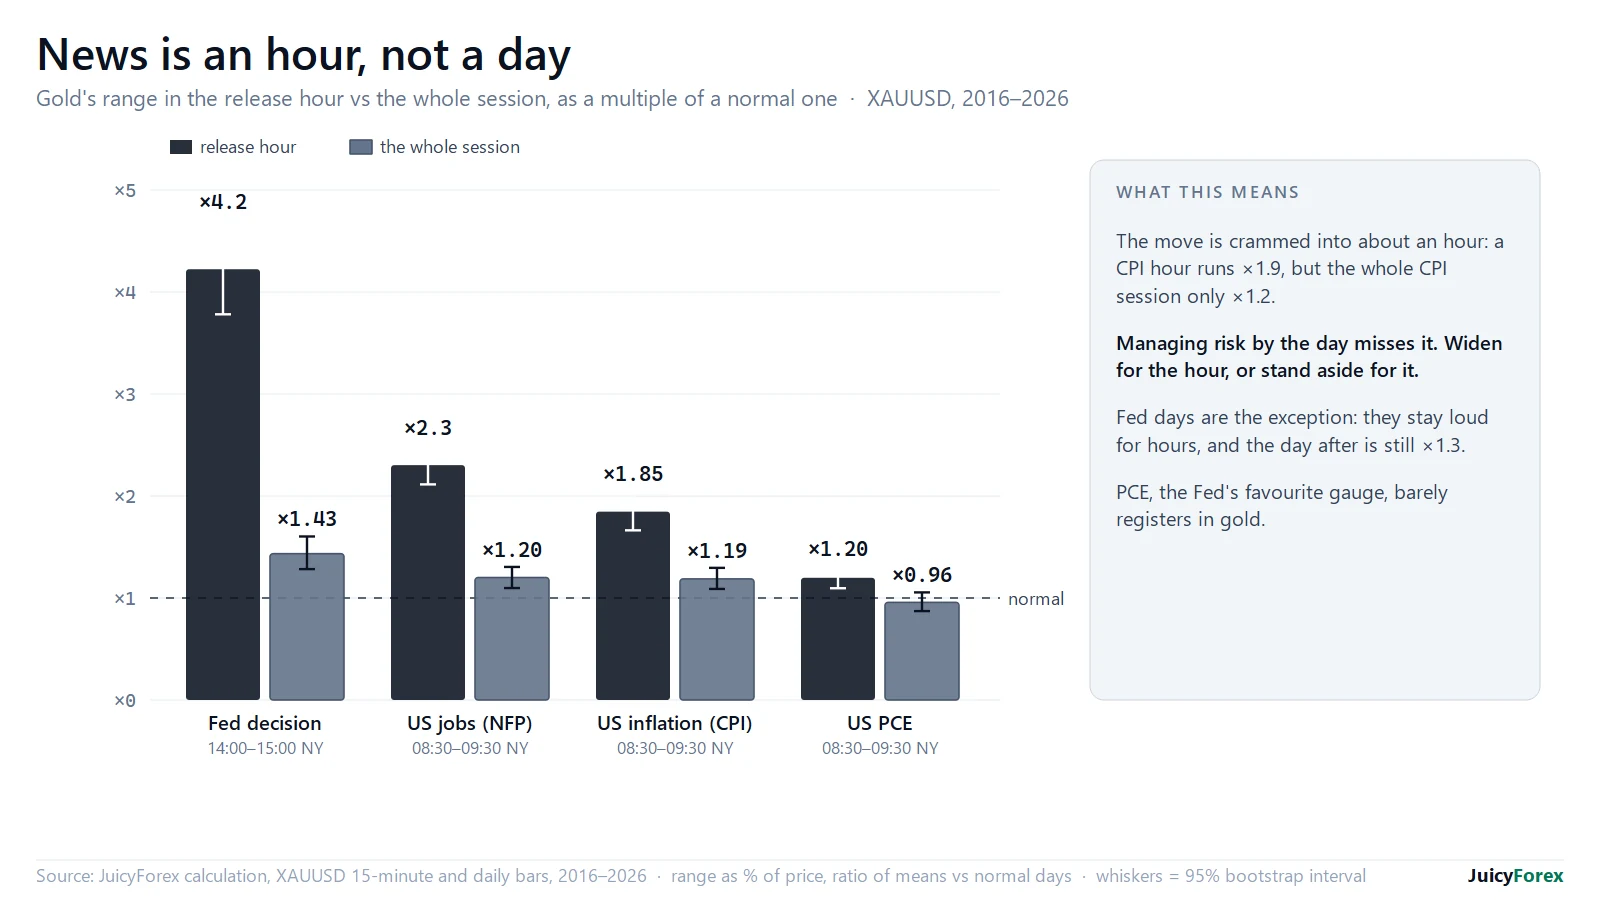
For gold, rising real yields were a headwind for stretches, even as safe-haven and other forces pulled the other way at times. It was a live demonstration of the chain: a Chair's policy, then real yields and the dollar, then every market.
The legacy and the debate
The episode cuts both ways.
- Critics argue the Fed was too slow in 2021 and had to tighten hard because it fell behind. That feeds the case for the rules-based approach associated with Warsh.
- Defenders say that once it moved, the Fed acted decisively and defended its credibility.
Either way, it is a case study in how policy transmits to prices. This is education, not advice.
Questions
How high did US inflation get in 2022?
Headline CPI peaked near 9% in mid-2022, the highest in about four decades. It was far above the Fed's 2% target and proving persistent.
How aggressively did the Powell Fed raise rates?
From near zero in early 2022, at the fastest pace in a generation. Several hikes were far larger than the usual quarter-point. It reached a restrictive range by mid-2023 while shrinking its balance sheet.
Was the Powell Fed too slow on inflation?
It is debated. Critics say it was too slow in 2021 and had to tighten harder. Defenders say it acted decisively once it moved.
70–80% of retail investor accounts lose money trading CFDs. This page is education, not advice. All trade examples are constructed composites.